

The Short Answer
Between February 2024 and July 2026, 36 residences closed at Oceana Bal Harbour. The median sale was $6,350,000 at $2,530 per square foot for 2,337 square feet, after a median 218 days under contract. Sales ran from $2,300,000 to $29,000,000.
Three findings here are worth more than the median, and two of them reverse what the same analysis found at Continuum on South Beach three weeks ago.
The real discount is 9%, not 6.5%. Sellers took 93.5% of their final asking price, the figure market reports quote. Measured against the price they first asked, they took 91.0%. At Continuum the same two numbers were 92.3% and 89.0%. The quoted statistic understates the discount in both buildings, by 2.5 points here and 3.3 points there.
Which tower is better depends entirely on residence size, and the answer flips. Among residences between 1,500 and 2,999 square feet, the North tower closed at $2,397 per square foot against the South tower’s $2,078. Among residences of 3,000 square feet and above, the South tower closed at $3,765 and the North at $2,787, and the South tower took 70 days to contract against the North tower’s 409.
The ocean view premium is real at Oceana, which it was not at Continuum. Comparing only South tower residences between 1,500 and 2,999 square feet, those whose MLS record says “Direct Ocean” closed at $2,519 per square foot against $1,819 for those that do not. That is a 38% premium surviving a control for both tower and size. At Continuum the same comparison collapsed to 3.3%.
And one number that does not need interpretation. The building’s highest closed sale is $29,000,000. One residence is currently asking $69,500,000, reduced from an original $75,000,000 after 307 days.
What Oceana Actually Trades At
| Measure | Closed residences, Feb 2024 to Jul 2026 |
|---|---|
| Closings | 36 |
| Median price | $6,350,000 |
| Median price per square foot | $2,530 |
| Median size | 2,337 SF |
| Median days to contract | 218 |
| Sold to final list price | 93.5% |
| Sold to original list price | 91.0% |
| Median monthly association fee | $4,540 |
| Range | $2,300,000 to $29,000,000 |
| Listings now active or pending | 17, median ask $5,650,000 |
| Listings that expired or withdrew | 6 |
Two things about the median are worth saying plainly. At 218 days, Oceana takes more than twice as long to go under contract as Continuum did at 93 days. And the 36 closings over 29 months mean the building turns over roughly 15 residences a year out of 239, which is a normal rate for a building of this calibre and not a sign of distress.
The six listings that expired or withdrew are 10% of the 59 listing attempts in this window. Continuum’s figure was 14%. Both are the part of the record a buyer never sees on a portal, because failed listings disappear.
The Real Discount: 9%, Not 6.5%
Market reports quote sold price against list price. At Oceana that is 93.5%, which reads as a 6.5% discount. But the list price on a closed record is frequently a reduced price rather than what the seller first asked.
This export carries the original list price, so the true figure is measurable: 91.0% of original asking, a 9.0% discount.
That the measurement replicates matters more than the number. At Continuum the gap between the two statistics was 3.3 points. Here it is 2.5. Two different buildings, two different submarkets, same direction. If you are working from sold-to-list alone, you are understating what sellers concede by roughly two to three points in both.
The building’s record sale shows how large the gap can get on an individual property. Residence 2601 in the South tower closed at $29,000,000 in September 2025 after 292 days. Its original asking price was $38,500,000. That sale took 75.0% of original asking, a 25% discount, and it is the highest price ever paid in the building.
One Listing Is Asking 2.4 Times the Building’s Record
In Miami’s Most Expensive Condo Buildings I measured the Ask Gap, the distance between what a building’s sellers ask and what the building has actually proven. Continuum was the first building where it inverted, with sellers asking 8% below the record.
Oceana is the opposite extreme.
| Measure | Oceana Bal Harbour | Continuum on South Beach |
|---|---|---|
| Highest closed sale | $29,000,000 | $23,900,000 |
| Highest current asking price | $69,500,000 | $22,000,000 |
| Highest original asking price | $75,000,000 | n/a |
| Ask Gap on current asking | 2.40x | 0.92x |
| Ask Gap on original asking | 2.59x | n/a |
Residence 2801 in the North tower, 8,993 square feet, came to market at $75,000,000, or $8,340 per square foot. It has been reduced to $69,500,000 and has been listed 307 days. The building’s record is $29,000,000 at $3,897 per square foot.
The second-highest listing, LPH 2701 in the North tower at 7,774 square feet, asks $38,500,000 at $4,952 per square foot after 217 days with no reduction.
Neither of those is a prediction that the residences are unsellable. They are penthouse-level properties and the building has only ever sold four residences above $17,500,000. What the gap does establish is that the asking side at Oceana carries no information about value. A buyer who anchors on $69,500,000 or $38,500,000 is anchoring on numbers the building has never supported.
And the contrast with Continuum is the real lesson. Two delivered trophy oceanfront buildings, nine miles apart, measured the same way three weeks apart. One has sellers asking below the record, the other has a listing at 2.4 times it. Seller discipline is a building-level fact. You cannot infer it from a market average, and you cannot infer it from the building next door.
Which Tower Is Better Depends Entirely on Size
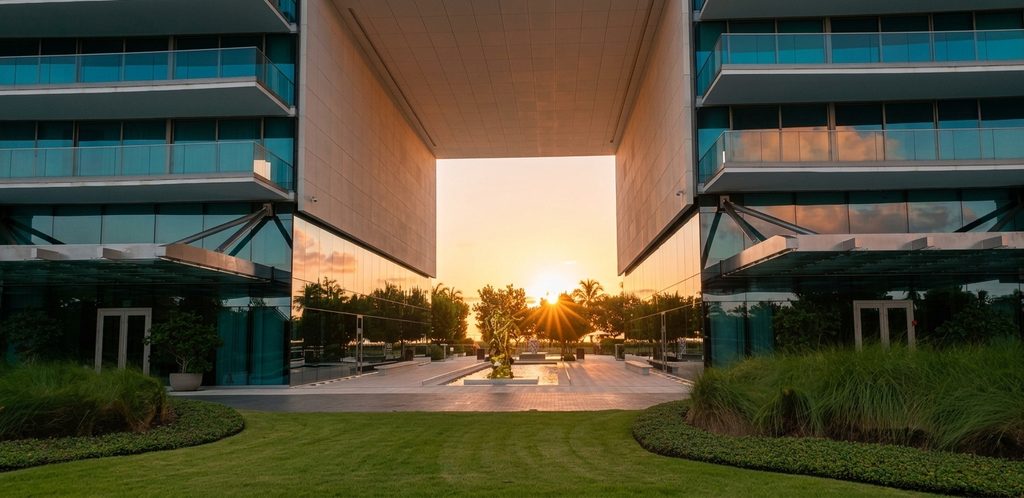
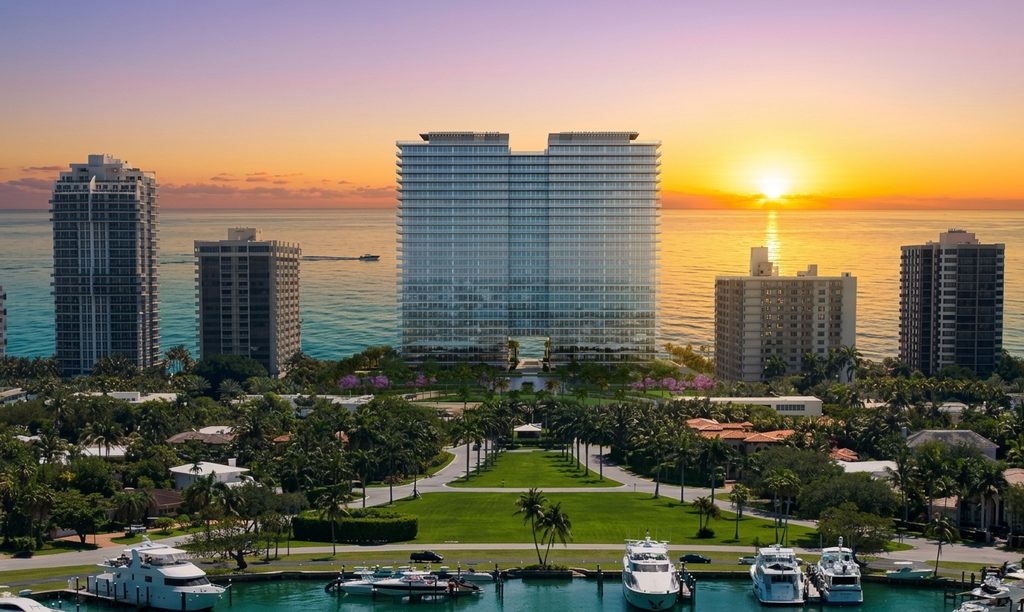
Oceana’s two towers are 10201 Collins Avenue, the South tower, and 10203 Collins Avenue, the North tower. Both delivered in 2016 and 2017. The raw medians say the North tower is the expensive one:
| Tower | Closings | Live listings | Median price | Median $/SF | Median size | Days to contract | Sold to original list | Median fee |
|---|---|---|---|---|---|---|---|---|
| North, 10203 Collins | 16 | 7 | $7,712,500 | $2,676 | 3,158 SF | 236 | 89.0% | $6,608 |
| South, 10201 Collins | 20 | 10 | $5,170,000 | $2,344 | 2,134 SF | 118 | 93.0% | $3,864 |
Read the size column before drawing a conclusion. The North tower’s median residence is 3,158 square feet and the South tower’s is 2,134. The towers do not hold the same product, so comparing their medians compares their floor plans.
Match the size and the answer splits in two:
| Size band | Tower | Closings | Median price | Median $/SF | Days to contract | Sold to original list |
|---|---|---|---|---|---|---|
| 1,500 to 2,999 SF | North | 8 | $5,450,000 | $2,397 | 193 | 91.5% |
| South | 13 | $3,750,000 | $2,078 | 216 | 93.5% | |
| 3,000 SF and up | North | 8 | $11,337,500 | $2,787 | 409 | 88.0% |
| South | 6 | $15,250,000 | $3,765 | 70 | 93.0% |
In the smaller band the North tower carries a 15% rate premium. In the larger band the South tower carries a 35% premium and goes under contract in 70 days against the North tower’s 409. That is not a small difference. It is a different market with a different outcome.
Eight and six closings per cell is thin and I am not going to pretend otherwise. But the days-to-contract gap in the larger band, 70 against 409, is too large to be noise, and it runs in the same direction as the discount figures, 93.0% against 88.0%. Three measures agreeing on six and eight closings is worth acting on, carefully.
The practical version: if you are buying a large residence at Oceana, the South tower has been the stronger and more liquid side. If you are buying a mid-size residence, the North tower has commanded more per foot. Anyone quoting you a tower-level average is quoting you a floor-plan mix.
At Oceana, the Ocean View Label Means Something
This is the finding that most clearly separates Oceana from Continuum, and I tested it three ways because the first result looked too good.
| Comparison | Closings | Median $/SF | Median size | Premium |
|---|---|---|---|---|
| “Direct Ocean”, all closings | 14 | $2,807 | 3,116 SF | +34% |
| Not “Direct Ocean”, all closings | 20 | $2,093 | 1,861 SF | |
| “Direct Ocean”, North tower only | 8 | $2,807 | 3,896 SF | +9% |
| Not “Direct Ocean”, North tower only | 8 | $2,567 | 2,542 SF | |
| “Direct Ocean”, South tower, 1,500 to 2,999 SF | 4 | $2,519 | 2,576 SF | +38% |
| Not “Direct Ocean”, South tower, 1,500 to 2,999 SF | 9 | $1,819 | 1,805 SF |
The premium survives controlling for tower and it survives controlling for size within a tower. At Continuum the same test collapsed the premium from 33% to 3.3%. Here it holds at 38% in the tightest cut available.
The reason is architectural rather than statistical. Continuum’s towers sit almost entirely on the beach, so nearly every residence has ocean exposure and the “Direct Ocean” label does not separate two different products. Oceana is laid out so that a meaningful share of residences face the bay, the gardens, the pool deck or the tennis courts instead. The label is doing real work because the building genuinely contains both.
The tightest comparison rests on four closings against nine, which is the thinnest figure in this analysis. Treat the direction as established and the magnitude as approximate.
The broader point stands against what I wrote about the View Label Illusion: the MLS view field is informative in some buildings and close to meaningless in others. Which one you are looking at cannot be known from the field itself. It has to be measured building by building.
Where Liquidity Breaks at Oceana
| Size band | Closings | Median price | Median $/SF | Days to contract | Sold to original list | Annual fee per SF |
|---|---|---|---|---|---|---|
| 1,500 to 1,999 SF | 11 | $3,450,000 | $2,025 | 119 | 94.0% | $25.07 |
| 2,000 to 2,999 SF | 10 | $6,162,500 | $2,530 | 212 | 91.0% | $25.47 |
| 3,000 to 4,499 SF | 10 | $11,337,500 | $2,903 | 260 | 91.0% | $23.03 |
| 4,500 SF and up | 4 | $21,750,000 | $3,375 | 364 | 88.0% | $22.59 |
Unlike Continuum, the rate at Oceana rises steadily with size and does not peak. What breaks is the time. Days to contract run 119, 212, 260 and 364 as residences get larger, and the share of original asking falls from 94.0% to 88.0%.
The Miami Condo Size Ceiling appears here as a liquidity effect rather than a pricing one, and it starts earlier than it did at Continuum. The penalty is visible by 2,000 square feet, where days nearly double against the band below it. At Continuum the break came at 4,000.
One closing fell below 1,500 square feet and is excluded from this table. The 4,500 and up band rests on four closings.
The Association Fee Is Proportional Here
Look at the last column of the table above. Annual fee per square foot runs $25.07, $25.47, $23.03 and $22.59 across the four bands, and the overall median is $4,540 a month.
That flatness is itself the finding. At Continuum the smallest residences paid $44.09 per square foot a year against $21.47 for the mid-size ones, roughly double. At Oceana the fee scales with the residence, so a buyer comparing a small Oceana unit to a small unit elsewhere is not absorbing a hidden penalty. My Miami Condo Carrying Costs analysis covers the method for working this into a purchase decision.
The towers differ sharply in absolute terms, a median $6,608 a month in the North tower against $3,864 in the South, but that tracks the 3,158 against 2,134 square foot difference in their median residences rather than a difference in the fee structure.
What Is for Sale Now
| Price tier | Closings | Share of sales | Live listings | Share of listings | Months of inventory |
|---|---|---|---|---|---|
| Under $4M | 12 | 33% | 8 | 47% | 21.9 |
| $4M to $7M | 10 | 28% | 4 | 24% | 13.1 |
| $7M to $15M | 9 | 25% | 3 | 18% | 10.9 |
| $15M and up | 5 | 14% | 2 | 12% | 13.1 |
Oceana carries 15.5 months of inventory overall, and the imbalance runs the opposite way from most buildings I have measured. The cheapest tier is the slowest. Eight of the 17 live listings are below $4,000,000, against 21.9 months of supply, while the $7,000,000 to $15,000,000 tier carries 10.9 months.
Across the Las Olas Isles, the Fort Lauderdale waterfront and Continuum, the pattern was the reverse: the entry tier cleared quickly and the trophy tier sat. At Oceana the smaller residences are the glut. If you are selling a sub-$4,000,000 residence here, you are competing with seven others and the building absorbs that tier slowly.
Two Residences Sold Twice
The Same-Unit Test I ran at Continuum needs repeat sales of the same residence, and Oceana’s 29-month window produced only two pairs. That is not enough for a finding, so here they are as a record rather than a conclusion.
| Residence | First sale | Second sale | Days held | Change |
|---|---|---|---|---|
| 302, North tower | $5,100,000 | $5,950,000 | 790 | +16.7% |
| 511, South tower | $3,950,000 | $3,750,000 | 447 | −5.1% |
One up, one down, on two pairs. Continuum produced nine pairs because its window ran 44 months against Oceana’s 29 and because it has been delivered since 2002 rather than 2016. A building that is ten years old has had fewer chances to trade the same residence twice.
Furniture did not matter here
At Continuum, furnished residences closed at the same rate as unfurnished but took three and a half times as long. That did not replicate. At Oceana, furnished residences closed at $2,564 per square foot against $2,526 unfurnished, took 212 days against 228, and held 90.0% of original asking against 91.0%. On 13 furnished closings against 23, there is no effect worth reporting in either direction.
What This Means If You Are Buying
Ask for the original list price on every comparable. The gap between 93.5% and 91.0% is two and a half points the standard statistic hides. On a $6,000,000 residence that is $150,000. The building’s record sale took 75.0% of its original asking.
Match the tower to the size you want. Large residence, look at the South tower first: $3,765 per square foot and 70 days to contract against the North tower’s $2,787 and 409 days. Mid-size residence, the North tower has commanded 15% more per foot.
The ocean label is worth paying for at this address, unlike at most. Matched for tower and size, direct ocean residences closed 38% above the rest. That premium is real here. Verify the exposure on the specific line rather than trusting the field, but do not assume the label is empty.
Below $4,000,000 you have leverage, not competition. Eight listings and 21.9 months of supply. That is the slowest tier in the building and the one place a patient buyer has the advantage.
Ignore the two largest asking prices entirely. A listing at $69,500,000 and another at $38,500,000 sit against a building record of $29,000,000 and only four sales above $17,500,000. They are not comparables for anything.
What This Means If You Are Selling
Price for 91%, not 93.5%. The median seller took 91.0% of what they first asked. Price to leave that room and you are pricing to the building’s actual pattern.
Expect 218 days, and longer if your residence is large. The median is 218 days to contract, and residences above 4,500 square feet took 364. Build the holding period into the decision before listing, not after the first ninety days.
If your residence is between 1,500 and 1,999 square feet, you are in the building’s fastest segment. Eleven closings took 94.0% of original asking in 119 days, the strongest combination of price and speed at Oceana. But check the tier table: that is also where the competing inventory sits.
Do not price against the headline listings. Two residences are asking more than twice what the building has ever achieved. If your comparables are those listings, you will join them on the market rather than in the sold column.
Frequently Asked Questions
What does a condo at Oceana Bal Harbour cost?
A median of $6,350,000. Across 36 closings between February 2024 and July 2026 the median was $6,350,000 at $2,530 per square foot for 2,337 square feet. Sales ranged from $2,300,000 to $29,000,000. The 17 residences currently listed ask a median $5,650,000.
How much do sellers at Oceana discount from the asking price?
About 9%. Sellers took a median 93.5% of their final list price but 91.0% of their original list price. The difference is the reductions taken before a contract, which the standard sold-to-list figure does not capture. The building’s record sale, residence 2601 at $29,000,000, took 75.0% of its $38,500,000 original asking price.
Is the North tower or the South tower better at Oceana Bal Harbour?
It depends on residence size, and the answer reverses. Among residences between 1,500 and 2,999 square feet, the North tower at 10203 Collins closed at $2,397 per square foot against the South tower’s $2,078. Among residences of 3,000 square feet and above, the South tower at 10201 Collins closed at $3,765 against the North tower’s $2,787, and went under contract in 70 days against 409. The raw tower medians favour the North tower only because its residences are larger.
How much is a direct ocean view worth at Oceana Bal Harbour?
A great deal, and this is unusual. Comparing only South tower residences between 1,500 and 2,999 square feet, those labeled “Direct Ocean” closed at $2,519 per square foot against $1,819 for those that are not, a 38% premium after controlling for both tower and size. The same test at Continuum on South Beach collapsed the premium to 3.3%. Oceana genuinely contains both ocean-facing and bay, garden and pool-facing residences, so the label separates two different products. That comparison rests on four closings against nine.
How long does an Oceana Bal Harbour condo take to sell?
A median 218 days to contract, more than twice Continuum’s 93 days. By size it runs 119 days for residences of 1,500 to 1,999 square feet, 212 for 2,000 to 2,999, 260 for 3,000 to 4,499 and 364 above 4,500. Six listings in this window, 10% of all listing attempts, expired or withdrew without selling.
Why is one Oceana condo asking $69.5 million?
Residence 2801 in the North tower, 8,993 square feet, came to market at $75,000,000 and has been reduced to $69,500,000 after 307 days. The building’s highest closed sale is $29,000,000, and only four residences have ever sold above $17,500,000. The asking price is 2.4 times the building’s record on its current figure and 2.59 times on its original. It is not a comparable for any other residence in the building.
What are the HOA fees at Oceana Bal Harbour?
A median $4,540 per month across closed sales, and the fee is proportional to size. Annual cost per square foot runs $25.07 for residences of 1,500 to 1,999 square feet, $25.47 for 2,000 to 2,999, $23.03 for 3,000 to 4,499 and $22.59 above 4,500. That flatness is worth noting, because at Continuum the smallest residences paid roughly double the per-foot rate of the mid-size ones. By tower the median is $6,608 in the North and $3,864 in the South, which tracks their residence sizes.
Have Oceana Bal Harbour condos appreciated?
Only two residences sold twice in this window, which is not enough to answer. Residence 302 in the North tower rose 16.7% over 790 days and residence 511 in the South tower fell 5.1% over 447 days. The building delivered in 2016 and 2017, so it has had fewer opportunities than an older building to trade the same residence twice.
Which price range at Oceana has the most inventory?
The bottom. Eight of the 17 live listings are below $4,000,000, against 21.9 months of supply, while the $7,000,000 to $15,000,000 tier carries 10.9 months. That is the reverse of most luxury buildings, where the entry tier clears fastest and the trophy tier sits. At Oceana the smaller residences are the slower half.
Does furniture add value at Oceana Bal Harbour?
No, and unlike at Continuum it does not cost time either. Furnished residences closed at $2,564 per square foot against $2,526 unfurnished, took 212 days against 228, and held 90.0% of original asking against 91.0%. On 13 furnished closings against 23 unfurnished, there is no measurable effect in either direction.
How does Oceana Bal Harbour compare to Continuum on South Beach?
Oceana’s median closing is $6,350,000 at $2,530 per square foot against Continuum’s $5,700,000 at $3,021. Oceana takes 218 days to contract against 93. Oceana’s sellers took 91.0% of original asking against Continuum’s 89.0%. The sharpest difference is the asking side: Continuum’s highest asking price sits 8% below its record sale, while Oceana carries a listing at 2.4 times its record. Both are delivered oceanfront trophy buildings, and almost nothing about their seller behaviour is the same.
Buying or Selling at Oceana Bal Harbour?
What an Oceana residence is worth cannot be reduced to the building’s name or to an average price per square foot. It depends on which tower, where the residence sits in the stack, what the line actually faces rather than what the listing says it faces, floor plan and whether the residence has been combined, the association fee measured against the square footage, what the original asking price was on every comparable rather than the reduced one, and how many residences of similar size are listed in both towers right now.
If you’re evaluating Bal Harbour real estate or a specific property at Oceana Bal Harbour, St. Regis Bal Harbour, Bellini, the Majestic Tower, Harbour House or Continuum on South Beach, contact Ashton Coleman for a property-specific comparison using recent closed sales and current competing inventory.
Explore current listings on Miami Penthouses & Estates.
📞 305.978.7704
📧 AColeman@onesothebysrealty.com
About the Market Data
This analysis uses a Southeast Florida MLS (SEFMLS) single-line export covering every listing at Oceana Bal Harbour, 10201 and 10203 Collins Avenue, with no price floor. The file holds 59 listing records: 36 closed sales, 16 active listings, one pending sale, five that expired and one withdrawn. Closings span February 23, 2024 through July 21, 2026, a period of about 29 months.
Two closed records are confidential sales carrying no list price, no original list price, no days on market and no association fee. They are residence 1701 in the South tower at $14,500,000 and residence 2001 at $16,000,000. Both are included in price, size and rate medians and excluded from every discount, days-to-contract and fee measure.
One closed record, residence 201 in the South tower, reports an original list price of $201, which is the unit number entered into the price field, producing a nonsense sold-to-original ratio. That record is excluded from the discount measure only. Its sale at $3,700,000 against a $5,040,000 list price is included everywhere else. The sold-to-original-list figure therefore rests on 33 of the 36 closings.
Price per square foot is taken from the MLS sold rate field, which is populated on every closed record. Two closed records carry no view description and are excluded from the direct ocean comparison only. Two active listings report an association fee of zero, which is missing data rather than a fee of zero, and are excluded from fee figures.
Sample sizes are stated beside every figure and several are small. The 4,500 and up size band rests on four closings, each tower cell in the size-matched comparison on six to thirteen, and the tightest direct ocean comparison on four closings against nine. The figures carrying real weight are the 36 closings in total, the 20 and 16 closings in the two towers, and the three size bands holding ten or eleven closings each.
The size-matched tower comparison is the method this analysis rests on most heavily, so its limits matter. Comparing tower medians directly would have shown the North tower as uniformly more expensive, which the size-matched figures contradict in the larger band. Where six and eight closings disagree with a simpler reading, I have reported the direction and said plainly that the magnitude is uncertain.
The direct ocean comparison uses the MLS unit view field, which is entered by the listing agent and is not standardized. A residence labeled “Direct Ocean” on a low floor behind an obstruction and one on a high floor with open water carry the same label. The finding here is that the label tracks value at this building, not that it is precise.
A year-by-year trend is not reported. Holding size constant, the 1,500 to 2,999 square foot band ran $2,188, $2,078 and $2,267 per square foot across 2024, 2025 and 2026 on seven, nine and five closings, and the 3,000 and above band ran $2,854, $2,603 and $3,017 on five, three and six. The unadjusted medians would have suggested a strong 2026, but that was a size mix effect, and the size-controlled cells are too small to carry a trend claim.
Months of inventory divides active and pending listings by the average monthly closing rate across the 29 months of closed data, and assumes forward absorption matches the trailing rate, which it will not exactly. One record reports an MLS area of 12 rather than 22; the discrepancy does not affect any calculation. Association fees are as reported on each listing record and do not reflect assessments, reserve contributions or subsequent increases. MLS information is believed accurate but is not guaranteed.
Disclaimer
Information is provided for informational purposes only and is subject to change without notice. Real estate statistics, listings and sales information should be independently verified. Nothing contained herein constitutes legal, tax, financial or investment advice. Buyers and sellers should consult appropriate professional advisors before making real estate decisions.