

The Short Answer
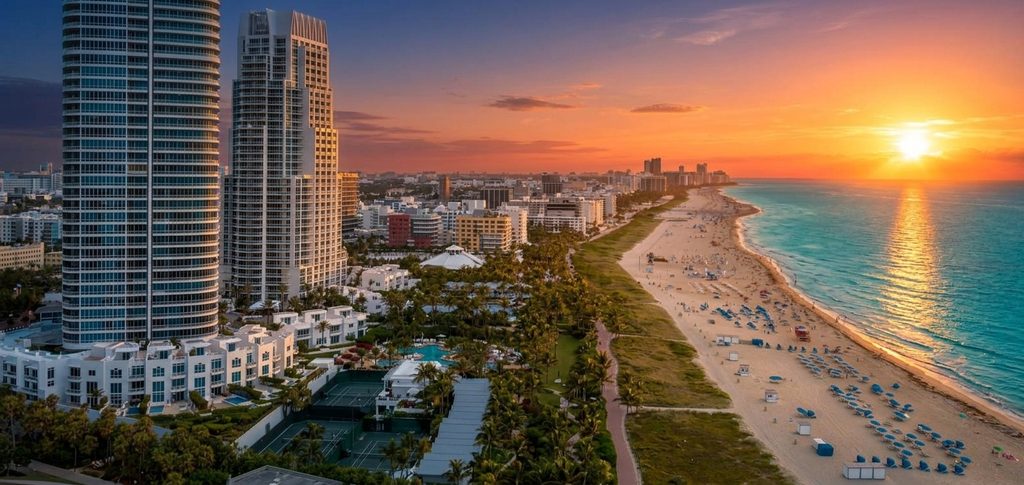
Between January 2023 and September 2026, 77 residences closed at Continuum on South Beach. The median sale was $5,700,000 at $3,021 per square foot for 1,862 square feet, after a median 93 days under contract. Sales ran from $1,400,000 to $23,900,000, a span of 17 times inside one gated oceanfront property.
Three things in this data are not available anywhere else, because they need the original asking price and the sale history of individual units rather than a market summary.
The real discount at Continuum is 11%, not 8%. Sellers took 92.3% of their final asking price, which is the figure every market report quotes. Measured against the price they first asked, they took 89.0%. The three points between those numbers are the price reductions that happen before a contract, and they are invisible in the usual statistic.
Nine residences sold twice in this window. Same unit, same line, same view, same floor. The median change between the two sales was positive 8.7% over a median hold of 371 days. Eight of the nine rose, one fell.
The direct ocean premium is almost entirely size. Residences whose MLS record says “Direct Ocean” closed at $3,564 per square foot against $2,683 for those that do not, which looks like a 33% premium for the water. Compare only residences between 1,400 and 2,999 square feet and that gap collapses to 3.3%.
What Continuum Actually Trades At
| Measure | Closed residences, Jan 2023 to Sep 2026 |
|---|---|
| Closings | 77 |
| Median price | $5,700,000 |
| Median price per square foot | $3,021 |
| Median size | 1,862 SF |
| Median days to contract | 93 |
| Sold to final list price | 92.3% |
| Sold to original list price | 89.0% |
| Median monthly association fee | $3,670 |
| Range | $1,400,000 to $23,900,000 |
| Listings now active or pending | 17, median ask $7,995,000 |
| Listings that expired, cancelled or withdrew | 15 |
The median is the number most often misquoted about this building. Continuum is known for its trophy sales, and it has them, but the median residence here traded at $5,700,000. Half of all closings were below that. The building contains a genuine range, from 609 square foot studios in the North tower to 5,049 square foot combinations in the South.
The 15 failed listings are worth as much attention as the 77 closings. Across 109 listing attempts in this window, 14% ended without a sale. That is the part of the record a buyer never sees on a portal, because expired and withdrawn listings disappear.
The Real Discount: 11%, Not 8%
Every market report, including mine, quotes sold price against list price. At Continuum that figure is 92.3%, which reads as a 7.7% discount.
That number uses the list price recorded on the closed sale, which is frequently a reduced price rather than what the seller first asked. This export carries the original list price, so the true figure is measurable for once: 89.0% of original asking, an 11.0% discount.
| Size band | Closings | Median price | Median $/SF | Days to contract | Sold to original list |
|---|---|---|---|---|---|
| Under 800 SF | 10 | $1,570,000 | $2,247 | 58 | 91.0% |
| 800 to 1,399 SF | 6 | $3,267,951 | $2,479 | 76 | 88.5% |
| 1,400 to 1,999 SF | 30 | $5,125,000 | $2,943 | 102 | 89.0% |
| 2,000 to 2,999 SF | 18 | $10,000,000 | $3,609 | 92 | 89.0% |
| 3,000 to 3,999 SF | 8 | $13,757,500 | $4,037 | 61 | 93.0% |
| 4,000 SF and up | 5 | $18,367,500 | $3,941 | 208 | 86.0% |
The discount is remarkably stable across the building at 88.5% to 91.0%, with two exceptions at the top. The 3,000 to 3,999 square foot band held 93.0% of original asking and sold in 61 days, the best outcome in the building. The 4,000 and up band took 86.0% after 208 days, the worst. Those rest on eight and five closings, so read them as a direction.
For a seller, the practical translation is this. If you want to net $5,000,000 on a 1,800 square foot residence, the evidence says to expect roughly $5,600,000 as a realistic original asking price, not $5,400,000.
The Same-Unit Test: Nine Residences That Sold Twice
I have used the Same-Building Test throughout this site, because comparing across buildings measures building mix rather than value. There is one step better, and Continuum has enough history to run it. Compare the same unit to itself.
When a residence sells twice, the floor is identical, the line is identical, the view is identical, the square footage is identical and the association is identical. Every variable that normally contaminates a comparison is held fixed. What remains is the market.
| Residence | First sale | Second sale | Days held | Change | Annualized |
|---|---|---|---|---|---|
| 2005, North | $3,800,000 | $5,050,000 | 170 | +32.9% | +84.2% |
| 3401, North | $10,800,000 | $13,765,000 | 292 | +27.5% | +35.4% |
| 3003, South | $12,000,000 | $14,765,000 | 81 | +23.0% | +154.6% |
| 702, South | $2,700,000 | $3,050,000 | 462 | +13.0% | +10.1% |
| 3205, South | $5,200,000 | $5,650,000 | 126 | +8.7% | +27.2% |
| 3402, South | $5,250,000 | $5,500,000 | 695 | +4.8% | +2.5% |
| 2305, North | $5,500,000 | $5,750,000 | 371 | +4.5% | +4.5% |
| 1206, South | $10,250,000 | $10,500,000 | 1,095 | +2.4% | +0.8% |
| 2005, North | $5,050,000 | $4,750,000 | 782 | −5.9% | −2.8% |
Median change positive 8.7% over a median 371 days held. Eight rose and one fell.
Read the first and last rows together, because they are the same residence. Unit 2005 in the North tower sold at $3,800,000, resold 170 days later at $5,050,000 for a 32.9% gain, then sold again 782 days after that at $4,750,000, giving back 5.9%. Over the full span it went from $3,800,000 to $4,750,000, a 25% gain across roughly two and a half years. The 84% annualized figure in the first row is arithmetic, not a return anyone should expect. It is what happens when you annualize a 170 day hold.
That is the honest lesson of the table. The two largest annualized numbers, on unit 3003 at 81 days and unit 2005 at 170 days, are the two shortest holds. The two longest holds, unit 1206 at 1,095 days and unit 3402 at 695 days, produced 0.8% and 2.5% a year. Short holds in this building have produced large numbers in both directions. Long holds have produced small ones.
Nine pairs is a small sample and one residence supplies two of them. Treat this as the best available evidence rather than as a settled rate of appreciation.
The Direct Ocean Premium Is Almost Entirely Size
This is the finding most likely to change how you read a Continuum listing.
| Comparison | Closings | Median $/SF | Median size | Apparent premium |
|---|---|---|---|---|
| MLS record says “Direct Ocean” | 35 | $3,564 | 2,048 SF | +32.8% |
| MLS record does not | 38 | $2,683 | 1,698 SF | |
| “Direct Ocean”, 1,400 to 2,999 SF only | 27 | $3,071 | 1,870 SF | +3.3% |
| Not “Direct Ocean”, 1,400 to 2,999 SF only | 19 | $2,974 | 1,791 SF |
Uncontrolled, direct ocean residences look 33% more valuable per square foot. Once you compare only residences of broadly similar size, the gap is 3.3%.
The reason is that the larger floor plans at Continuum are concentrated on the ocean side. So the raw comparison is measuring floor plan, not water. This is the View Label Illusion appearing inside a single building, and it is stronger here than I have measured anywhere else.
That does not mean the ocean view is worth nothing. It means the MLS view field is a poor instrument for pricing it. Two residences on the same line, four floors apart, with the same label, can have materially different water exposure depending on what sits in front of them. The label does not capture that and neither does the rate.
At Oceana Bal Harbour the same test produced the opposite result. There the premium held at 38% after controlling for both tower and size, because that building genuinely contains bay, garden and pool-facing residences alongside ocean-facing ones. The field is a poor instrument at Continuum and a reliable one at Oceana, and nothing in the field itself tells you which case you are looking at.
Furnished Residences Took Three Times as Long for the Same Price
Comparing only residences between 1,400 and 2,999 square feet, so size is held roughly constant:
| Condition | Closings | Median $/SF | Median days to contract | Sold to original list |
|---|---|---|---|---|
| Unfurnished | 33 | $3,088 | 78 | 89.5% |
| Furnished | 11 | $3,049 | 275 | 89.0% |
| Partially furnished | 4 | $3,304 | 78 | 84.0% |
Furnished and unfurnished residences closed at the same rate, $3,049 against $3,088, and took the same share of original asking. The difference is time. Furnished residences took a median 275 days to contract against 78 days unfurnished, which is three and a half times longer.
I have written before that furniture does not add to price. This data says something sharper. Furniture did not reduce the price at Continuum either. It reduced the pool of buyers willing to take it, and that cost the seller six months.
Eleven furnished closings is a thin sample and the partially furnished row rests on four. The time gap is large enough to be worth knowing anyway.
Where the Size Ceiling Falls in This Building
The rate climbs with size up to a point, then liquidity breaks. Returning to the size table above, price per square foot runs $2,247, $2,479, $2,943, $3,609, then peaks at $4,037 in the 3,000 to 3,999 band, then falls to $3,941 above 4,000 square feet.
At the same time the 4,000 and up band took 208 days to contract against 61 days for the band below it, and 86.0% of original asking against 93.0%.
That is the Miami Condo Size Ceiling reproduced inside one address, which matters because the market-wide version of that finding could always be challenged as a building mix effect. It cannot be challenged here. The ceiling at Continuum falls at about 4,000 square feet, and five closings sit above it.
On floor height, the pattern holds and it is modest once size is controlled. Within the 1,400 to 1,999 square foot band, closings on floors 5 to 14 ran $2,715 per square foot, floors 15 to 24 ran $2,881, and floors 25 and above ran $3,046. That is 12.2% from the lowest band to the highest, consistent with the building-level figure in The Floor Curve. In the 2,000 to 2,999 band the pattern is not monotonic and each cell holds three to seven closings, so it should not be read.
South Tower and North Tower Are Not the Same Market
| Tower | Closings | Live listings | Median price | Median $/SF | Median size | Days to contract | Sold to original list |
|---|---|---|---|---|---|---|---|
| South, 100 South Pointe Drive (2002 to 2003) | 45 | 12 | $5,995,000 | $3,244 | 1,870 SF | 78 | 89.0% |
| North, 50 South Pointe Drive (2008) | 32 | 5 | $4,575,000 | $2,876 | 1,698 SF | 115 | 90.0% |
The South tower is five to six years older and trades 12.8% higher per square foot. It also sells faster, 78 days against 115.
Age is not driving this and neither is condition. Position is. The South tower sits closer to the point at the south end of the property with the wider ocean frontage and the more open southern exposure. The North tower, completed later, sits behind it. The newer building is the cheaper one, which is the reverse of what holds across almost every Miami submarket I have measured.
The North tower’s slightly better share of original asking, 90.0% against 89.0%, is within noise on 32 and 45 closings.
What the Core Segment Has Done Since 2023
The building’s deepest segment is the 1,400 to 1,999 square foot band, with 30 closings. Holding size constant that way is the only honest method for a trend inside one building, because the yearly mix of large and small residences shifts.
| Year closed | Closings in band | Median price | Median $/SF | Median days to contract |
|---|---|---|---|---|
| 2023 | 6 | $5,600,000 | $3,147 | 68 |
| 2024 | 10 | $5,225,000 | $2,964 | 70 |
| 2025 | 7 | $5,250,000 | $2,807 | 336 |
| 2026, through September | 7 | $4,460,000 | $2,674 | 252 |
The rate has fallen every year since 2023, from $3,147 to $2,674 per square foot, a decline of 15.0%. Days to contract roughly quadrupled between 2024 and 2025 and stayed high.
Note what the unadjusted numbers would have told you. The building’s overall median price rose from $5,700,000 in 2023 to $6,700,000 in 2025 before falling in 2026. That rise was a mix effect. Hold size constant and the core segment has softened steadily for three years.
Each year in this table rests on six to ten closings, which is thin, and 2026 covers roughly nine months. The direction is consistent across all four years, which is why I am reporting it, but a single year’s figure here should not be used as a benchmark.
The Ask Gap Inverts at Continuum
In Miami’s Most Expensive Condo Buildings I measured the Ask Gap, the distance between what a building’s sellers ask and what the building has actually proven. Across the market it runs the wrong way, with asking prices well above any closed evidence.
Continuum is the first building where it reverses. The highest current asking price is $22,000,000. The highest closed sale was $23,900,000, unit 2803 in the South tower in December 2025. The ratio is 0.92 to 1. Sellers here are asking less than the building has already achieved.
On a rate basis the picture is different and worth holding alongside it. Live listings ask a median $3,981 per square foot against a closed median of $3,021. That is a 31.8% gap, and it is mostly the same composition effect that shows up everywhere: the larger and better positioned residences are the ones currently listed.
Oceana Bal Harbour is the other extreme. Measured the same way three weeks later, its highest closed sale is $29,000,000 while one residence is currently asking $69,500,000, reduced from an original $75,000,000 after 307 days. That is an Ask Gap of 2.40 to 1 against Continuum’s 0.92. Seller discipline is a building-level fact rather than a market-level one, and it does not carry from one trophy oceanfront building to the next.
What Is for Sale Now
| Price tier | Closings since Jan 2023 | Share | Live listings | Share | Months of inventory |
|---|---|---|---|---|---|
| Under $3M | 11 | 14% | 2 | 12% | 8.1 |
| $3M to $6M | 32 | 42% | 4 | 24% | 5.5 |
| $6M to $12M | 20 | 26% | 6 | 35% | 13.3 |
| $12M and up | 14 | 18% | 5 | 29% | 15.9 |
Overall the building carries 9.8 months of inventory. The $3,000,000 to $6,000,000 tier is the tightest at 5.5 months and it produced 42% of all closings. Above $6,000,000 inventory runs 13 to 16 months against 44% of closings.
This is a milder version of the imbalance I found across the Fort Lauderdale waterfront and in the Miami condo market generally. Continuum’s top end is slow, but at 13 to 16 months it is nowhere near the two to six year supply that trophy inventory carries in less liquid markets. The building’s trophy segment actually trades.
One footnote worth knowing: the cabanas
Three sales in this period were not residences. Two beach cabanas of about 400 square feet closed at $2,400,000 and $1,910,000, or $6,000 and $4,775 per square foot. A 450 square foot unit closed at $1,500,000, or $3,333. All three exceed the per-foot rate of every residence in the building, including the $23,900,000 top sale at $5,004 per square foot.
They are excluded from every figure above, because including them would distort the rate medians. They are a useful reminder that price per square foot measures scarcity, not space.
What the Association Fee Actually Costs
| Size band | Closings | Median monthly fee | Annual cost per square foot |
|---|---|---|---|
| Under 800 SF | 10 | $2,647 | $44.09 |
| 1,400 to 1,999 SF | 28 | $3,542 | $23.96 |
| 2,000 to 2,999 SF | 16 | $4,486 | $21.47 |
| 3,000 SF and up | 10 | $8,013 | $26.66 |
The small residences carry roughly twice the association cost per square foot of the mid-size ones, $44.09 a year against $21.47. A 700 square foot residence paying $2,647 a month is paying for the same oceanfront acreage, staff and amenity program as a 2,800 square foot residence paying $4,486.
For a buyer comparing a studio here against a larger residence elsewhere, that is the number that belongs in the calculation alongside the purchase price. My Miami Condo Carrying Costs analysis covers the full method.
What This Means If You Are Buying
Do not pay the ocean label premium. Matched for size, direct ocean residences closed 3.3% above the rest. If a listing is priced 25% above a comparable residence of similar size on the strength of its view field, the closed evidence does not support that.
The $3,000,000 to $6,000,000 tier is the competitive one. Four listings against 32 closings and 5.5 months of supply. That is where you move quickly. Above $6,000,000 you have 13 to 16 months of inventory and time to work.
Ask for the original list price on every comparable. The gap between 92.3% and 89.0% is three points of negotiating context that the standard statistic hides. On a $6,000,000 residence that is about $198,000.
Above 4,000 square feet, expect to be the one with leverage. Five closings in that band took a median 208 days and 86.0% of original asking. The largest residences are the slowest to move here.
Furnished is an opportunity, not a premium. Furnished residences closed at the same rate as unfurnished and sat three and a half times longer. A furnished listing approaching six months on market is a motivated seller.
What This Means If You Are Selling
Price for 89%, not 92%. The building’s median seller took 89.0% of what they first asked. If you price to leave room, you are pricing to the pattern. If you price at the number you want, the evidence says you will arrive there anyway after reductions and a longer wait.
Your tower matters more than your vintage. The South tower trades 12.8% higher per square foot and sells 37 days faster despite being the older building. Comparables from the other tower need that adjustment before they mean anything.
If you are selling furnished, decide what the furniture is worth to you. It did not raise the rate and it did not lower it. It cost the median furnished seller about six months.
If your residence is between 3,000 and 3,999 square feet, you are in the building’s best segment. Eight closings took 93.0% of original asking in 61 days, the strongest combination of price and speed anywhere in the building.
The building’s ceiling is proven, so do not ask below it. The highest close is $23,900,000 and the highest current ask is $22,000,000. Continuum is one of very few Miami buildings where sellers are asking under the established record rather than over it.
Frequently Asked Questions
What does a condo at Continuum South Beach cost?
A median of $5,700,000. Across 77 residence closings between January 2023 and September 2026 the median was $5,700,000 at $3,021 per square foot for 1,862 square feet. Sales ranged from $1,400,000 for a small North tower residence to $23,900,000 for unit 2803 in the South tower. The 17 residences currently listed ask a median $7,995,000.
How much do sellers at Continuum discount from the asking price?
About 11%. Sellers took a median 92.3% of their final list price, but 89.0% of their original list price. The difference is the reductions taken before a contract, which the standard sold-to-list statistic does not capture. The pattern is stable across the building, between 88.5% and 91.0% in every size band except the two at the top.
Is the North tower or the South tower better at Continuum?
The South tower trades higher and sells faster. Across 45 closings the South tower, at 100 South Pointe Drive and built 2002 to 2003, closed at a median $3,244 per square foot in 78 days. Across 32 closings the North tower, at 50 South Pointe Drive and built 2008, closed at $2,876 per square foot in 115 days. The older tower is 12.8% more expensive per square foot, which reflects its position closer to the southern point rather than its age or condition.
How much is a direct ocean view worth at Continuum?
Much less than the raw numbers suggest. Residences whose MLS record says “Direct Ocean” closed at $3,564 per square foot against $2,683 for those that do not, an apparent 33% premium. Comparing only residences between 1,400 and 2,999 square feet, the gap falls to 3.3%, $3,071 against $2,974. The larger floor plans at Continuum sit on the ocean side, so the uncontrolled comparison is measuring floor plan rather than water.
Have Continuum condos appreciated?
Nine residences sold twice in this window, and the median change between the two sales was positive 8.7% over a median 371 days held. Eight of the nine rose and one fell. The largest annualized figures came from the shortest holds, so they should not be read as expected returns. The two longest holds, 1,095 and 695 days, produced 0.8% and 2.5% a year. Separately, the building’s core 1,400 to 1,999 square foot segment has declined from $3,147 to $2,674 per square foot between 2023 and 2026.
Is the Continuum market getting stronger or weaker?
Weaker in the core segment. Holding size constant in the 1,400 to 1,999 square foot band, which carries 30 closings, the rate fell each year from $3,147 per square foot in 2023 to $2,964, then $2,807, then $2,674 through September 2026, a decline of 15.0%. Days to contract rose from 68 to 252. The building’s unadjusted median price rose over the same period, which was a size mix effect rather than appreciation. Each year rests on six to ten closings.
How long does a Continuum condo take to sell?
A median 93 days to contract across all 77 closings. By size, the 3,000 to 3,999 square foot band was fastest at 61 days and the 4,000 and up band was slowest at 208 days. Furnished residences between 1,400 and 2,999 square feet took a median 275 days against 78 days for unfurnished. Fifteen listings in this window, 14% of all listing attempts, expired, cancelled or withdrew without selling.
What are the HOA fees at Continuum South Beach?
A median $3,670 per month across closed sales, but the figure depends heavily on size. Residences under 800 square feet paid a median $2,647 a month, which is $44.09 per square foot per year. Residences between 2,000 and 2,999 square feet paid $4,486, which is $21.47 per square foot per year. Residences above 3,000 square feet paid $8,013. The smallest residences carry roughly twice the association cost per square foot of the mid-size ones.
Does furniture add value at Continuum?
No, and it costs time. Comparing residences between 1,400 and 2,999 square feet, furnished units closed at $3,049 per square foot and unfurnished at $3,088, which is effectively the same, and both took about 89% of original asking. Furnished residences took a median 275 days to contract against 78 days unfurnished. The sample is 11 furnished closings against 33 unfurnished.
Why did a Continuum cabana sell for $6,000 per square foot?
Because price per square foot measures scarcity rather than space. Two beach cabanas of about 400 square feet closed at $2,400,000 and $1,910,000, or $6,000 and $4,775 per square foot, which exceeds the rate of every residence in the building including the $23,900,000 top sale at $5,004 per square foot. There are a fixed number of cabanas and they cannot be built. They are excluded from every residence figure in this analysis.
Are sellers at Continuum asking more than the building has sold for?
No, and that is unusual. The highest current asking price is $22,000,000 against a highest closed sale of $23,900,000, a ratio of 0.92 to 1. Across most Miami luxury buildings the asking side sits well above any closed evidence. On a per square foot basis live listings do ask a median $3,981 against a closed median of $3,021, but that gap is mostly composition, because the larger and better positioned residences are the ones currently listed.
Buying or Selling at Continuum on South Beach?
What a Continuum residence is worth cannot be reduced to the building’s name or to an average price per square foot. It depends on which tower, where the residence sits in the stack, what the line looks at and what could change in front of it, floor plan and whether the residence has been combined, interior condition and the vintage of the last renovation, the association fee against the square footage, what the original asking price was on every comparable rather than the reduced one, and how many residences of similar size are listed in both towers right now.
If you’re evaluating a property at Continuum South Beach, Oceana Bal Harbour, The Surf Club, Estates at Acqualina, Jade Signature, One Thousand Museum, Five Park, Faena House, Apogee or any Miami Beach, Bal Harbour, Sunny Isles or Key Biscayne building, contact Ashton Coleman for a property-specific comparison using recent closed sales and current competing inventory.
Explore current listings on Miami Penthouses & Estates.
📞 305.978.7704
📧 AColeman@onesothebysrealty.com
About the Market Data
This analysis uses a Southeast Florida MLS (SEFMLS) single-line export covering every listing at Continuum on South Beach, 50 and 100 South Pointe Drive, Miami Beach real estate, with no price floor. The file holds 112 listing records: 80 closed sales, 17 active or pending listings, and 15 that expired, cancelled, withdrew or terminated. Closings span January 5, 2023 through September 16, 2026, a period of about 44 months.
Three closed sales were cabanas or units of 450 square feet or less and are excluded from every residence figure, leaving 77 residence closings. They are reported separately in their own section. Excluding them matters: including a 400 square foot cabana at $6,000 per square foot would distort every rate median in this analysis.
Price per square foot is taken from the MLS sold rate field, which is populated on every closed record in this export. Sold to original list price uses the MLS SP/OLP field, which is absent on four closed records; those four are excluded from that measure only. Four closed records carry no view description and are excluded from the direct ocean comparison only.
Combined residences are reported by the MLS as single sales under paired unit numbers such as 2608/2609 and 1906/07. They are treated as one sale at their combined square footage, which is how they transacted. They are not repeat sales of one unit.
The repeat-sale table pairs consecutive closed sales of the same unit number in the same tower, requiring at least 30 days between them so that a corrected or re-reported sale is not counted as a resale. Nine pairs result, and unit 2005 in the North tower supplies two of them, so the table describes eight distinct residences. Annualized figures on holds under six months are arithmetic artifacts and are labeled as such in the text. Nine pairs is a small sample and no appreciation rate should be drawn from it.
Sample sizes are stated beside every figure and several are small. The 3,000 to 3,999 square foot band rests on eight closings, the 4,000 and up band on five, the furnished comparison on eleven, the partially furnished row on four, and each cell of the year-by-year table on six to ten. The figures that carry real weight are the 77 residence closings in total, the 30 closings in the 1,400 to 1,999 square foot band, and the 45 and 32 closings in the two towers.
The 2026 row covers January 22 through September 16, roughly nine months, so its closing count is not comparable to a full year. The year-by-year trend holds size constant deliberately, because the yearly mix of large and small residences shifts enough to move an unadjusted median in the opposite direction from the underlying rate.
Months of inventory divides current active and pending listings by the average monthly closing rate across the 44 months of closed data, and assumes forward absorption matches the trailing rate, which it will not exactly.
The direct ocean comparison uses the MLS unit view field, which is entered by the listing agent and is not standardized. A residence labeled “Direct Ocean” on a low floor behind an obstruction and one on a high floor with open water carry the same label. That imprecision is part of the finding rather than a flaw in it, but it means the 3.3% figure measures the label and not the view.
One closed record reports a year built of 2024 for a tower completed in 2002 and 2003, which is most likely a renovation year entered in the wrong field. Year built is otherwise consistent at 2002 and 2003 for the South tower and 2008 for the North, and the field is not used in any calculation here. Association fees are as reported on each listing record and do not reflect assessments, reserves contributions or subsequent increases. MLS information is believed accurate but is not guaranteed.
Disclaimer
Information is provided for informational purposes only and is subject to change without notice. Real estate statistics, listings and sales information should be independently verified. Nothing contained herein constitutes legal, tax, financial or investment advice. Buyers and sellers should consult appropriate professional advisors before making real estate decisions.